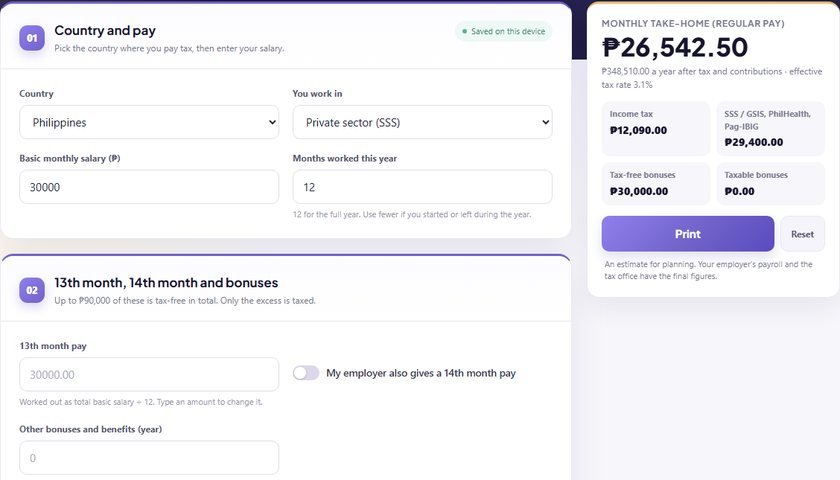
Every payslip for a private employee in the Philippines has the same four deductions. This guide shows how each is computed for the employee share, with a complete example for a ₱30,000 monthly salary.
SSS
The total SSS contribution is 15% of the monthly salary credit (MSC): 10% from the employer and 5% from the employee. The MSC is your salary rounded to the nearest ₱500 bracket, with a minimum of ₱5,000 and a maximum of ₱35,000 for the regular contribution. The employer also pays the Employees’ Compensation premium.
Salary ₱30,000 → MSC ₱30,000 → employee share ₱1,500.
PhilHealth
The premium is 5% of the basic monthly salary, shared equally, so the employee pays 2.5%. Salaries below ₱10,000 are computed at ₱10,000, and salaries above ₱100,000 at ₱100,000.
Salary ₱30,000 → employee share ₱750.
Pag-IBIG (HDMF)
Employees earning over ₱1,500 pay 2%, and the employer adds 2%, on a maximum monthly fund salary of ₱10,000. In practice most employees pay ₱200 a month.
Withholding tax
Tax is computed on taxable compensation: gross pay minus the employee’s SSS, PhilHealth and Pag-IBIG contributions and other non-taxable items. The annual rates under the TRAIN law from 2023 onward are:
| Annual taxable income | Tax |
|---|---|
| ₱250,000 or less | 0 |
| Over ₱250,000 to ₱400,000 | 15% of the excess over ₱250,000 |
| Over ₱400,000 to ₱800,000 | ₱22,500 + 20% of the excess over ₱400,000 |
| Over ₱800,000 to ₱2,000,000 | ₱102,500 + 25% of the excess over ₱800,000 |
| Over ₱2,000,000 to ₱8,000,000 | ₱402,500 + 30% of the excess over ₱2,000,000 |
| Over ₱8,000,000 | ₱2,202,500 + 35% of the excess over ₱8,000,000 |
For a monthly payroll, the same brackets divided by 12 are used: nothing on the first ₱20,833 of monthly taxable pay, then 15% of the excess up to ₱33,333, and so on. The 13th-month pay and other benefits up to ₱90,000 a year are tax-exempt, and so are de minimis benefits within their limits.
Complete example: ₱30,000 a month
| Basic salary | ₱30,000.00 |
| SSS (5% of ₱30,000 MSC) | − ₱1,500.00 |
| PhilHealth (2.5%) | − ₱750.00 |
| Pag-IBIG | − ₱200.00 |
| Taxable compensation | ₱27,550.00 |
| Withholding tax: 15% × (27,550 − 20,833) | − ₱1,007.55 |
| Net pay | ₱26,542.45 |
On a semi-monthly payroll, many employers deduct half of each contribution every cutoff; others deduct SSS on one cutoff and PhilHealth and Pag-IBIG on the other. Either is fine as long as the monthly total is right.
Overtime, night shift and holidays
Under the Labor Code, overtime on an ordinary working day is paid at the hourly rate plus 25%. Work between 10 PM and 6 AM earns a night shift differential of at least 10% of the hourly rate. Work on a regular holiday is paid at 200% of the daily rate, and on a special non-working day at 130%. These are added to gross pay and are taxable unless covered by an exemption, such as for minimum wage earners.
Make the payslips
The payroll and payslip generator applies these rates, adds overtime, allowances and other deductions, and prints two payslips per page. Rates change from time to time, so check the latest SSS, PhilHealth, Pag-IBIG and BIR circulars before each year’s first payroll.